Discover the future of Firm AI for the business of law
On November 10, see how Intapp Celeste brings Firm AI to life as the operating layer for professional firms.
· 11 min read
The COVID-19 pandemic has caused a drop in total volume of legal services demanded. Firms are seeking to manage their immediate exposure, and to successfully emerge from the downturn in the coming months.
Intapp anticipates that law firms will manage through five waves of COVID-19 adjustments:
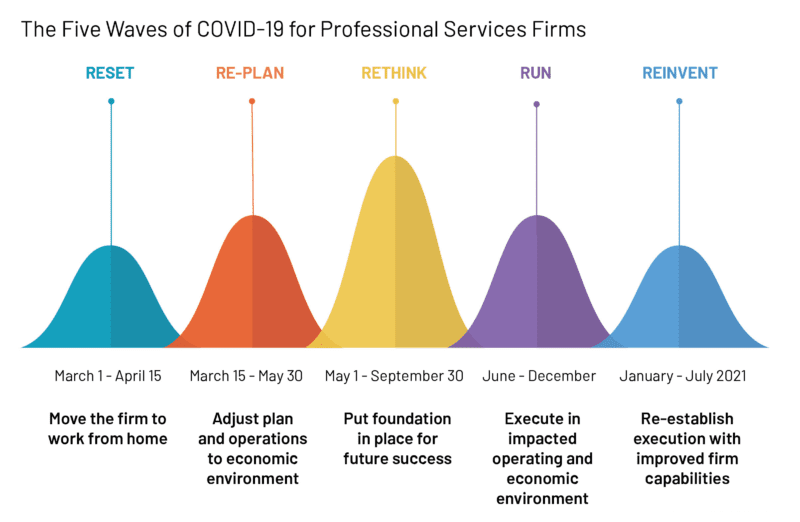
To date, many firms have completed the reset and re-plan transition phases, and instated new financial plans for the firm that include a modified model for legal services delivery. Some key examples include withholding partner distributions, introducing of stringent cash management measures, and ramping up resources in counter-cyclical practice areas (e.g., restructuring and insolvency).
Intapp Strategic Consulting has leveraged statistical analysis of past public health and financial crises in order to help law firms make data-driven decisions as they move into the rethink wave of adjustment.
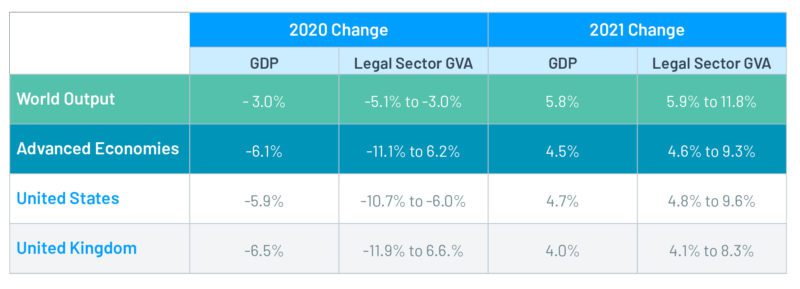
The impacts of COVID-19 on global GDP are estimated to be significant, with advanced economies — like the U.S. — seeing an anticipated GDP hit of 5.9% in 2020 before rebounding in 20211.
Many law firms are now trying to quantify the associated impact of the current recession on their businesses in order to support planning for their practices and operations during the coming year. Although like-for-like comparisons are challenging, given the global scope of this public health crisis, our analysis on past data seeks to understand the correlation between GDP and the prosperity of the legal sector.
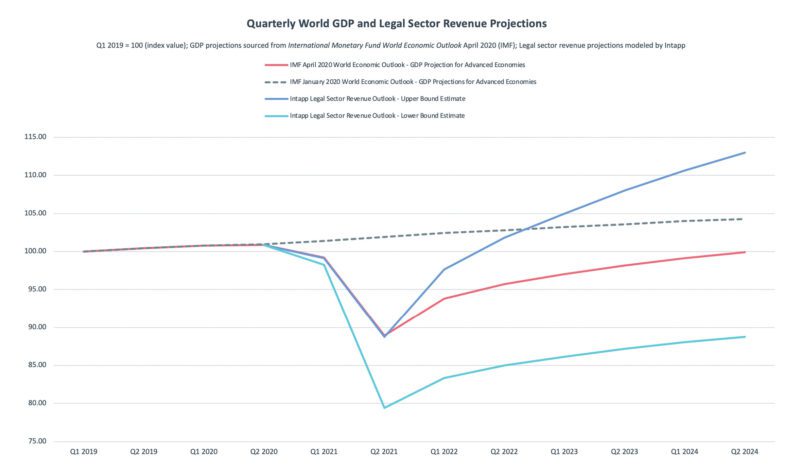
Our findings indicate that the correlation between GDP and legal sector outlooks is positive and significant at the 95% confidence level. Further, the analysis indicates that between 36% and 47% of the change in the value of legal sector revenues is historically explained by changes in the economy.
Based on International Monetary Fund (IMF) April 2020 GDP projections for advanced economies, the most likely impact of COVID-19 on total legal sector revenue is estimated between -6.2% and -11.1%. Our analysis has also identified outlier data that suggest far more positive and negative potential scenarios; however these outcomes are unlikely.
Lessons from the last financial crisis indicate that there will be both winners and losers. Analysis of strategies used by leading law firms that benefited during the last recession offer particular insights. Supporting AM Law data suggests that, for example:
That said, today’s recession offers many differences that firms should bear in mind.
It’s not all doom and gloom, and firms that focus on certain industries and practice areas will do well. In alignment with this understanding, Intapp has projected demand impacts across industries and practices for the next 6 months (as illustrated in the Intapp Demand Impact Model).
Many firms have yet to quantify these changes in market opportunities. Quantitative analysis and other supporting research will help illuminate the likely magnitude of the impact to law-firm business volumes, and will inform the next critical steps toward supporting business planning and investment decisions across firms’ practices.
For example, our analysis has determined that during the 2008–2009 financial crisis, patent applications in the U.S. fell from 485,312 in 2008 to 482,871 in 2009 (a change of -0.5%)4. Research has shown that IP filings are correlated with business cycles and are pro-cyclical5. Research firms are thus predicting that filing activities could fall 2% to 4% in 2020 and 20216.
Beyond the Intapp Strategic Consulting quantitative analysis, we have also corresponded with senior law firm leaders to qualitatively understand their short- and medium-term considerations. Some of these include:
Finally, those firms that make the right investments and apply data-driven thinking to decision-making, will be best placed to win in the future.
For more information on helping your firm weather upcoming uncertainties, visithttps://intapp.wpenginepowered.com/pages/strategic-consulting-covid-19-business-impact/
| Table 1. Tests of Normality | ||
| Assumption/Test | ||
| Residuals follow normal distribution | Test Value | Prob Value |
| United States | ||
| Shapiro Wilk | 0.94274 | 0.07443 |
| Skewness | -0.5519174 | – |
| Kurtosis | 1.355055 | – |
| United Kingdom | ||
| Shapiro Wilk | 0.95426 | 0.3577 |
| Skewness | -0.5714448 | – |
| Kurtosis | -0.4590729 | – |
| Hong Kong | ||
| Shapiro Wilk | 0.91045 | 0.08763 |
| Skewness | -0.8165996 | – |
| Kurtosis | 1.505715 | – |
| Table 2: Regression Statistics | |
| United Kingdom | |
| Multiple R | 0.692580406 |
| R Square | 0.479667619 |
| Adjusted R Square | 0.454889887 |
| P-value | 0.000249748 |
| Standard Error | 1.227231969 |
| Hong Kong | |
| Multiple R | 0.636749287 |
| R Square | 0.405449654 |
| Adjusted R Square | 0.368290258 |
| P-value | 0.004488991 |
| Standard Error | 0.050320337 |
| United States | |
| Multiple R | 0.697288104 |
| R Square | 0.4862107 |
| Adjusted R Square | 0.469636852 |
| P-value | 0.00000650911 |
| Standard Error | 0.020108537 |
1 IMF World Economic Outlook, April 2020: https://www.imf.org/en/Publications/WEO
2 As per the OECD, Gross Value Added (GVA) is an economic productivity metric that measures the contribution to the economy of each individual producer, industry or sector. It is an important metric because it is used to adjust GDP.
3Legal and Accounting Services definition: This division includes legal representation of one party’s interest against another party, whether or not before courts or other judicial bodies by, or under supervision of, persons who are members of the bar, such as advice and representation in civil cases, advice and representation in criminal actions, advice and representation in connection with labour disputes. It also includes preparation of legal documents such as articles of incorporation, partnership agreements or similar documents in connection with company formation, patents and copyrights, preparation of deeds, wills, trusts, etc. as well as other activities of notaries public, civil law notaries, bailiffs, arbitrators, examiners and referees. It also includes accounting and bookkeeping services such as auditing of accounting records, preparing financial statements and bookkeeping.
4 U.S. Patent Statistics, U.S. Patent and Trademark Office, https://www.uspto.gov/web/offices/ac/ido/oeip/taf/us_stat.html
5Evidence from European Patent Office Filings, ‘Do Business Cycles Affect Patenting?’ http://fs2.american.edu/wgp/www/EPO_BusCycle.pdf. Forecasting Patent Filings at the European Patent Office (EPO) with a Dynamic Log Linear Regression Model: Applications and Extensions http://fs2.american.edu/wgp/www/ACEB%20Singapore.pdf
6 Bloomberg article ’Patent Filings, Litigation May Shift in Economic Crisis’, https://news.bloomberglaw.com/ip-law/patent-filings-litigation-may-shift-in-economic-crisis
From the blog
VP, GM Time
Engagement intelligence links time, terms, and outcomes so each matter sharpens the next one’s pricing and staffing. See how law firms compound profitability.
Generate pitchbooks, tombstones, and credentials from Intapp DealCloud data with Pitchly, so bankers spend less time formatting and more time winning mandates.
Carr, Riggs & Ingram M&A Advisors selects Intapp DealCloud with Celeste to apply governed, agentic Firm AI to its mergers, acquisitions, and deal management processes.